Have Strong Assets but Variable Income? You May Have More Mortgage Options
What if you have plenty of money saved or invested, but your income doesn't look strong enough to qualify for the mortgage you want?
This is a situation we see more often than you might think.
You may have substantial retirement savings, investment accounts, cash reserves, or other assets, but your traditional qualifying income may not tell the whole story.
Maybe you're retired. Maybe you're self-employed. Maybe your income is heavily commission-based. Maybe you recently sold a business. Or perhaps most of your wealth is sitting in investments rather than coming from a traditional paycheck.
The good news is that some mortgage programs may allow eligible assets to be considered when determining how much you can qualify for.
At JPAL Mortgage, we've dealt with these scenarios before! We're happy to determine if "assets as income" may fit your situation.
Let's discuss! 616-465-5725
Or click here to text and schedule a call.
Can You Qualify for a Mortgage Using Assets?
Potentially, yes.
Depending on the mortgage program and lender, certain financial assets may be used in different ways when determining whether you qualify for a mortgage.
This can be particularly helpful when your traditional income is relatively low, inconsistent, difficult to document, or doesn't accurately reflect your overall financial position.
For example, imagine someone has:
- Significant balances in retirement and investment accounts
- A relatively modest amount of taxable income
- Very little traditional employment income
- A strong credit history
- A substantial down payment available
A traditional income-based qualification may not tell the entire story.
That's where asset-based mortgage qualification and asset depletion programs may become worth exploring.
The important part is that there isn't one calculation that applies to every borrower. The treatment of assets depends on the specific loan program, the type of account, the borrower's circumstances, and the lender's requirements.
What Is an Asset Depletion Mortgage?
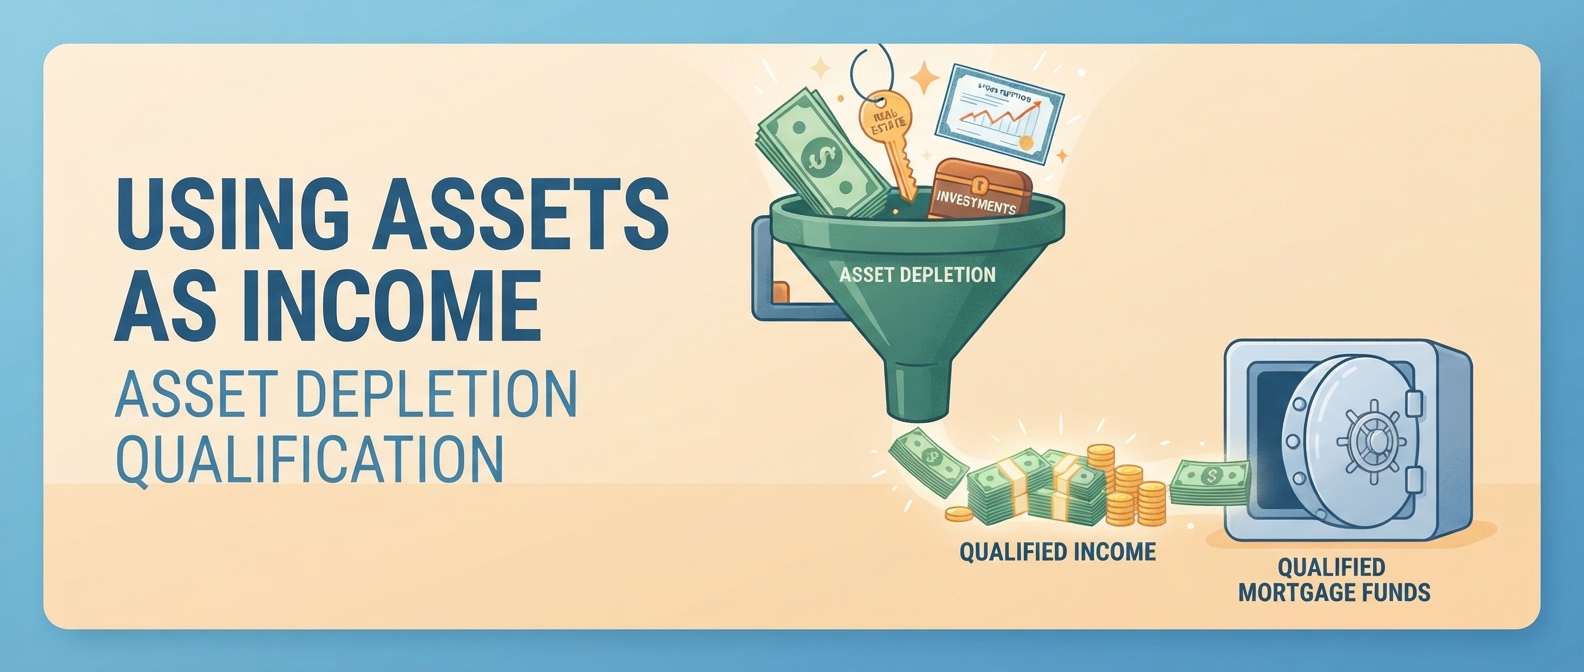
An asset depletion mortgage is a type of mortgage qualification strategy where eligible assets may be converted into a calculated amount of qualifying income for underwriting purposes.
Instead of looking only at your paycheck or other recurring income, the lender may be able to consider certain financial assets when determining your ability to qualify.
For example, a borrower who has significant retirement or investment assets but relatively little traditional income may have an option that isn't available through a standard income-only qualification.
Asset depletion is particularly relevant for borrowers whose wealth is concentrated in assets rather than employment income.
It's important to understand the distinction
An asset depletion calculation doesn't necessarily mean that you are withdrawing money from your retirement account every month.
In many cases, the calculation is an underwriting method used to determine qualifying income.
The actual rules depend on the mortgage program and lender.
What Types of Assets May Be Considered?
Depending on the mortgage program, lenders may consider various types of financial assets.
These can potentially include:
Retirement Accounts
Examples can include:
- 401(k) accounts
- Traditional IRAs
- Roth IRAs
- Other eligible retirement accounts
Retirement assets can be particularly important for retirees and borrowers who have accumulated significant savings but no longer have substantial employment income.
Investment Accounts
Certain investment and brokerage accounts may also be considered, including accounts containing:
- Stocks
- Bonds
- Mutual funds
- Other eligible investments
The treatment of investment assets can vary, so the type of account and the assets inside it matter.
Cash and Other Financial Assets
Depending on the program, other liquid financial assets may also play a role in qualification.
This is why it's important to have us review the actual accounts rather than assuming that every dollar of every account will be treated the same way.
A Pause In The Action!
We have successfully used the "Asset Depletion" income model several times! We also have multiple options for this - conventional or "Non QM". If you have questions or want to prepare a mortgage plan, let's schedule a time to discuss! 616-465-5725
Or click here to text and schedule a call.
Who Might Benefit From Asset-Based Mortgage Qualification?
Asset-based qualification can be worth exploring for several different types of borrowers.
Retirees
You may have accumulated significant wealth in retirement accounts and investments but no longer have a traditional paycheck.
Your retirement assets could potentially play a role in qualifying for a mortgage.
Self-Employed Borrowers
Business owners sometimes have substantial assets but complicated income documentation.
If your tax returns don't tell the entire story of your financial position, it may be worth exploring whether an asset-based mortgage strategy could help.
Former Business Owners
If you've recently sold a business or have accumulated significant assets through your business, your current income may look very different from your overall financial position.
There may be mortgage programs worth exploring beyond a traditional income calculation.
Investors
Real estate investors and other investors may have substantial assets while maintaining relatively little traditional employment income.
The right mortgage program may allow some of those assets to be considered.
Commission-Based or Variable-Income Borrowers
If your income fluctuates substantially from year to year, qualifying income can sometimes be more complicated.
Assets may provide another avenue to explore, depending on the circumstances.
Can Retirement or Investment Assets Be Used to Qualify for a Mortgage?
Potentially, yes.
This is one of the most common questions we hear from borrowers with significant savings.
However, the answer isn't simply:
"You have $X in investments, so the lender will count $X as income."
That's not how it works.
Depending on the mortgage program, the lender may apply specific rules to determine how much of your assets can be considered and how they can contribute to qualifying income.
Factors can include:
- The type of account
- Whether the assets are liquid
- Whether the borrower owns the assets
- The amount of the down payment
- The mortgage program
- The lender's underwriting requirements
- Documentation of the assets
- And others
That's why two borrowers with the same account balance could potentially have different qualification results.
Michigan Asset Depletion Loans
If you're buying a home in Michigan and have significant assets but limited or variable income, Michigan asset depletion loans may be worth investigating.
These programs can be particularly relevant for borrowers who don't fit the traditional W-2 borrower profile.
At JPAL Mortgage, we work with borrowers throughout Michigan and can look at your individual situation to determine what mortgage programs may be available.
You don't have to know whether you need an "asset depletion loan" before contacting us.
That's our job.
We'll look at the big picture:
- Your income
- Your assets
- Your credit
- Your debts
- Your down payment
- The property you're purchasing
- Your overall financial situation
Then we can discuss the mortgage options that may make sense to investigate.
A Pause In The Action!
We have successfully used the "Asset Depletion" income model several times! We also have multiple options - conventional or "Non QM". If you have questions or want to prepare a mortgage plan, let's schedule a time to discuss! 616-465-5725
Or click here to text and schedule a call.
What Documentation Will You Need?
If you're exploring an asset-based mortgage, expect the lender to document the assets being considered.
Depending on the program, this may include documentation such as:
- Recent account statements
- Retirement account statements
- Investment account statements
- Verification of ownership
- Documentation showing the source of funds
- Other financial documentation required by the specific mortgage program
The lender will need to determine which assets are eligible and how those assets can be treated under the applicable underwriting guidelines.
Don't assume an account qualifies—or doesn't qualify—until the mortgage lender reviews it.
What If I Have Strong Assets but Low Income?
This is probably the most important takeaway from this entire page:
Low traditional income doesn't automatically mean you have no mortgage options.
If you have significant assets, there may be mortgage programs that look at more than just your employment income.
That doesn't mean every borrower with substantial assets will qualify.
Credit, debt, down payment, property type, loan amount, asset type, documentation and other factors still matter.
But if you've been told:
"Your income isn't high enough for the house you want."
and you have substantial financial assets, it may be worth getting a second look at your situation.
Why Work With a Mortgage Broker?
Asset-based mortgage qualification can get complicated quickly.
There isn't necessarily one mortgage program that works for every borrower with significant assets.
As a mortgage broker, JPAL Mortgage can look across available mortgage options rather than assuming that a single loan program is the answer.
You don't need to walk into the conversation knowing the name of the loan you need. Just bring us the details of your financial situation.
Phone: 616-465-5725
Email: hello@jpalmortgage.com
What happens when you contact JPAL:
Frequently Asked Questions About Asset Depletion Income
Can I qualify for a mortgage using my assets instead of income?
Potentially. Certain mortgage programs may allow eligible assets to be considered when determining qualifying income. The specific calculation depends on the loan program, lender, asset type and borrower circumstances.
What is an asset depletion mortgage?
An asset depletion mortgage uses a lender's underwriting methodology to convert certain eligible assets into a calculated amount of qualifying income. The borrower does not necessarily have to withdraw that amount from the account each month.
Can I use my 401(k) to qualify for a mortgage?
Potentially. Some mortgage programs may allow eligible retirement assets to be considered in qualification. The exact treatment depends on the account, loan program and lender requirements.
Can investment accounts help me qualify for a mortgage?
Potentially. Certain investment and brokerage assets may be considered under some mortgage programs. The lender will need to verify the assets and determine how they can be treated under the applicable guidelines.
Are there asset depletion loans in Michigan?
Yes, mortgage programs involving asset-based qualification may be available to eligible Michigan borrowers. Availability and requirements vary by lender and loan program.
Can I qualify for a mortgage if I'm retired but have substantial assets?
Potentially. Retirees with significant retirement and investment assets may have mortgage options that consider those assets, depending on the specific loan program and financial circumstances.
Can self-employed borrowers use assets to qualify for a mortgage?
Potentially. Self-employed borrowers with substantial assets and complicated or variable income may have asset-based mortgage options worth exploring.
Do I have to withdraw money from my retirement account?
Not necessarily. In an asset depletion calculation, the lender may use a formula to determine qualifying income from eligible assets. This is different from actually withdrawing that amount from the account.
How much do I need in assets to qualify?
There is no single asset amount that applies to every mortgage program. The amount needed depends on the loan amount, down payment, debts, income, asset type, credit profile and the specific lender and program.
How do I find out whether my assets can help me qualify?
The best way is to have a mortgage loan originator review your complete financial picture. JPAL Mortgage can look at your income, assets, debts and home-buying plans and help determine which mortgage options may be worth exploring.
616-465-5725
hello@jpalmortgage.com
JPAL Mortgage – Your best friend in home finance.
All loans require complete underwriting approval, including satisfactory appraisal and clear title work. Interest rates and closing costs are subject to change. NMLS ID #2189752 | Equal Housing Opportunity.
Want to drill down deeper? Check out additional "Asset Depletion" thoughts here!
What do clients say about us?
"Jeremy helped us with the purchase of our very first home. He was extremely helpful throughout the entire process. He answered every question we had - big or small - as if it was the most important thing he could be doing in that moment. He made us feel very cared for and was extremely efficient at giving us updates along the way. Do not question your choice to work with Jeremy! We are so glad we did."
— JUSTINE L.
"Adam made the lending process super easy and worry free. Very responsive and willing to take the time to educate throughout the process. Incredibly quick to close as well. Highly recommend for all your mortgage needs!"
"It was a pleasure working with Ryan! He was timely and knowledgeable about the industry. Ryan makes the home buying process enjoyable!"
"JPAL is absolutely fantastic! I've worked with Jeremy on multiple mortgages and he always impresses and delivers! What Jeremy and Adam are building at JPAL is excellent for all homeowners. I very highly recommend JPAL!!"
"Travis Hunt is the best mortgage professional I've worked with! He is knowledgeable, has great communication throughout the process and always puts the client's needs first! I'd recommend Travis Hunt and JPAL to anyone!"